Imagine getting a $400,000 offer on your Pocono home. You're ready to celebrate until you notice the buyer wants $10,000 toward closing costs.
Well, that's a plot twist.
Seller credits aren't necessarily a bad thing. Sometimes they're exactly what gets a deal across the finish line. But before you start handing out money, there's something you should know:
the buyer's mortgage gets a vote, too.
Under Fannie Mae's conventional loan guidelines, seller contributions for investment properties are generally capped at 2%. On a $400,000 property, that's $8,000, assuming the appraisal supports the price.
So that $10,000 request? The extra $2,000 exceeds the limit and can create a financing problem.
For primary residences and second homes, the limits are different, ranging from 3% to 9%, depending on the loan-to-value ratio.
That's why I don't recommend agreeing to a seller credit without understanding the buyer's financing first.
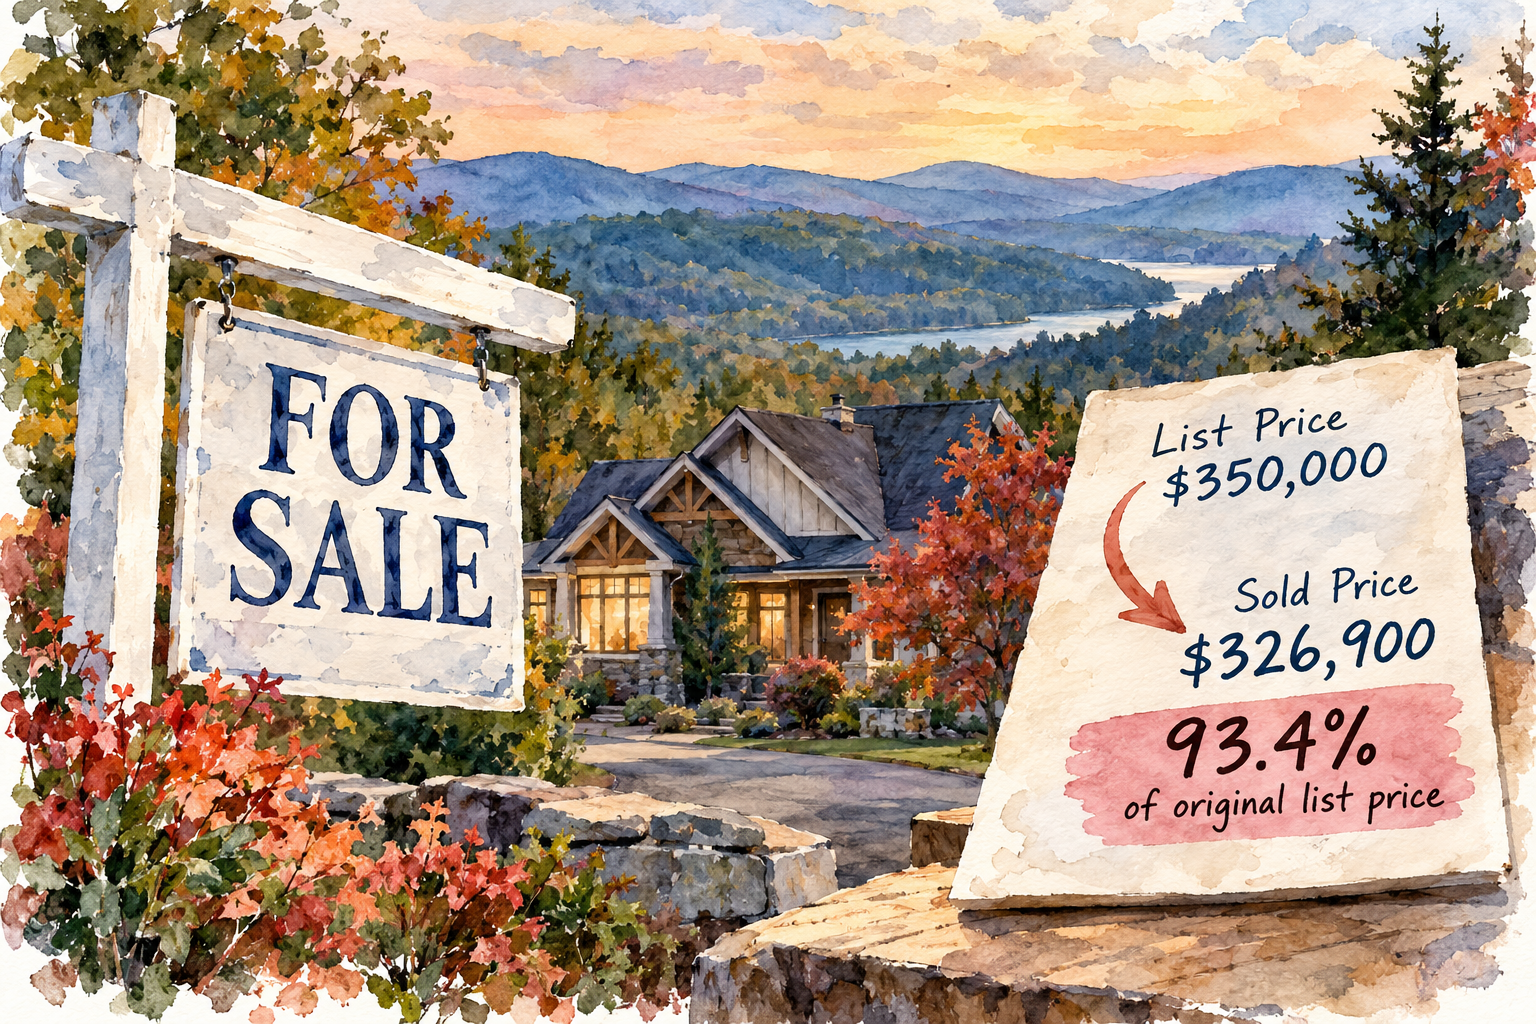
And this conversation is particularly relevant in Monroe County right now. According to the Pocono Mountains Association of Realtors, September's median sales price was $339,500, up 1.3% from a year earlier. But sellers received an average of just 93.4% of their original asking prices. Translation? Home prices haven't fallen off a cliff, but buyers aren't necessarily paying what sellers hoped they'd get.
There's another detail those sales figures don't show: seller concessions. A home can close at $400,000 while the seller contributes $8,000 toward the buyer's costs. The recorded sale price still says $400,000. The seller's bank account tells a slightly different story.
Meanwhile, Freddie Mac reported that the average 30-year mortgage rate dipped to 7.24% on October 29. That's welcome news, but hardly a return to bargain-basement borrowing.
Buyers are still watching their monthly payments, and sellers are looking for ways to keep deals together. That's where credits can be useful.
But here's where I draw the line:
Don't negotiate based on how good the offer looks. Negotiate based on what you'll actually keep.
A $392,000 offer without concessions might be worth comparing with a $400,000 offer that includes an $8,000 credit. Once you factor in closing expenses, financing, and appraisal risk, the better offer isn't always the one with the bigger number.
The Pocono market isn't falling apart. It's simply asking sellers to be a little more strategic. And frankly, that's not a bad thing.
Before you celebrate the number on the contract, make sure you've done the math on the number you'll take home.
Thinking about selling in Monroe County? Let's look at what your property could realistically sell for and what you'd actually walk away with. Text or DM
VALUE.
Alexa Sanchez, REALTOR® | Smart Way America Realty
PA License #RS326383
(570) 688-8147 |
Alexa@alexasanchez.net
Sources: PMAR September 2026 Monthly Indicators; Freddie Mac October 29, 2026; Fannie Mae Selling Guide B3-4.1-02.